Life insurance document generation software: a guide for life and annuity carriers
Life insurance document generation software for a carrier is a CCM platform that produces policy contracts matching filed forms, annual statements and in-force correspondence for policies that stay on the books for decades, plus the annuity disclosures and replacement letters NAIC model rules require. Illustration and suitability tools handle the point of sale; CCM handles everything after. Quadient Inspire, OpenText Exstream, Oracle Documaker and Experlogix have the clearest documented life or annuity evidence.
Shopping for life insurance document generation software? Know what makes life and annuity different first. A whole life policy or deferred annuity can stay in force for 40 years, and every annual statement, in-force illustration and replacement letter you send in that time has to match rules written for that product.
This guide covers the NAIC rules that shape life and annuity documents, the clocks they set, and which customer communications management (CCM) platforms have documented life or annuity evidence. It isn’t legal advice. For property and casualty and general insurance requirements, see CCM software for insurance. For the full vendor list, see our CCM software guide.
Pick by your situation
Short on time? Start here.
- Running Sapiens CoreSuite for Life & Annuities? Look at Quadient Inspire, which Sapiens announced as an integration partner.
- Big annual statement and correspondence runs, in more than one language? Look at OpenText Exstream.
- Already on Oracle for policy admin? Look at Oracle Documaker, and ask how it connects to your release.
- Mid-sized carrier on Microsoft tools? Look at Experlogix.
- Running SmartCOMM today? Jump to renewal and exit terms.
Where illustration tools end and CCM begins
Life and annuity searches mix up two kinds of software. Illustration and annuity sales tools sit with the producer. They calculate projected values and capture the suitability record at the point of sale.
CCM takes over once the application is in. It composes the contract against the filed form, then produces every statement, notice and letter for as long as the policy lives. Ask any vendor that claims both to show you each one separately.
Four NAIC models shape most life and annuity documents
The NAIC writes model regulations; each state adopts its own version. These four drive most template work, and your compliance team will know which state variations apply.
Illustrations: guaranteed values first, signed and numbered
Model 582 covers life policies sold with an illustration. Each page is numbered against the total (“page 4 of 7”), guaranteed values come before non-guaranteed ones, and the numeric summary shows policy years 5, 10 and 20 and age 70.
If the policy issues differently from what was applied for, a revised illustration is signed no later than delivery. Variable life and annuities sit outside this model.
Annual reports and in-force illustrations for decades
For policies sold with an illustration, Model 582 also requires a yearly report with values, death benefit and loans. If it doesn’t include an in-force illustration, it must tell the owner how to ask for one and to contact the state insurance department if none arrives within 30 days.
Any adverse change in non-guaranteed elements gets disclosed prominently. That makes your annual run a regulated document job, not just a statement print.
Annuity disclosure and best interest
Model 245 requires a disclosure document and the Buyer’s Guide at or before application when you sell face to face. Otherwise you send them within five business days of receiving the application, and the buyer gets at least a 15-day free look.
Model 275 adds the best-interest standard. The producer’s disclosure form goes out before the recommendation, and signed consumer statements are needed when someone refuses to give information or buys without a recommendation. The NAIC says 49 jurisdictions had implemented the 2020 revisions by August 2025.
Replacement: two carriers, two five-day clocks
Model 613 kicks in when a new policy replaces an existing one. The applicant and producer sign the Notice Regarding Replacement no later than the application. The replacing insurer then has five business days to notify the existing insurer and must offer a 30-day free look.
The existing insurer must send the owner a letter offering current policy values, such as an in-force illustration or policy summary, and has five business days to provide them once the owner asks. So you need to generate this letter and those values on demand, fast, for any policy you’ve ever written.
Every life and annuity document has a trigger and a clock
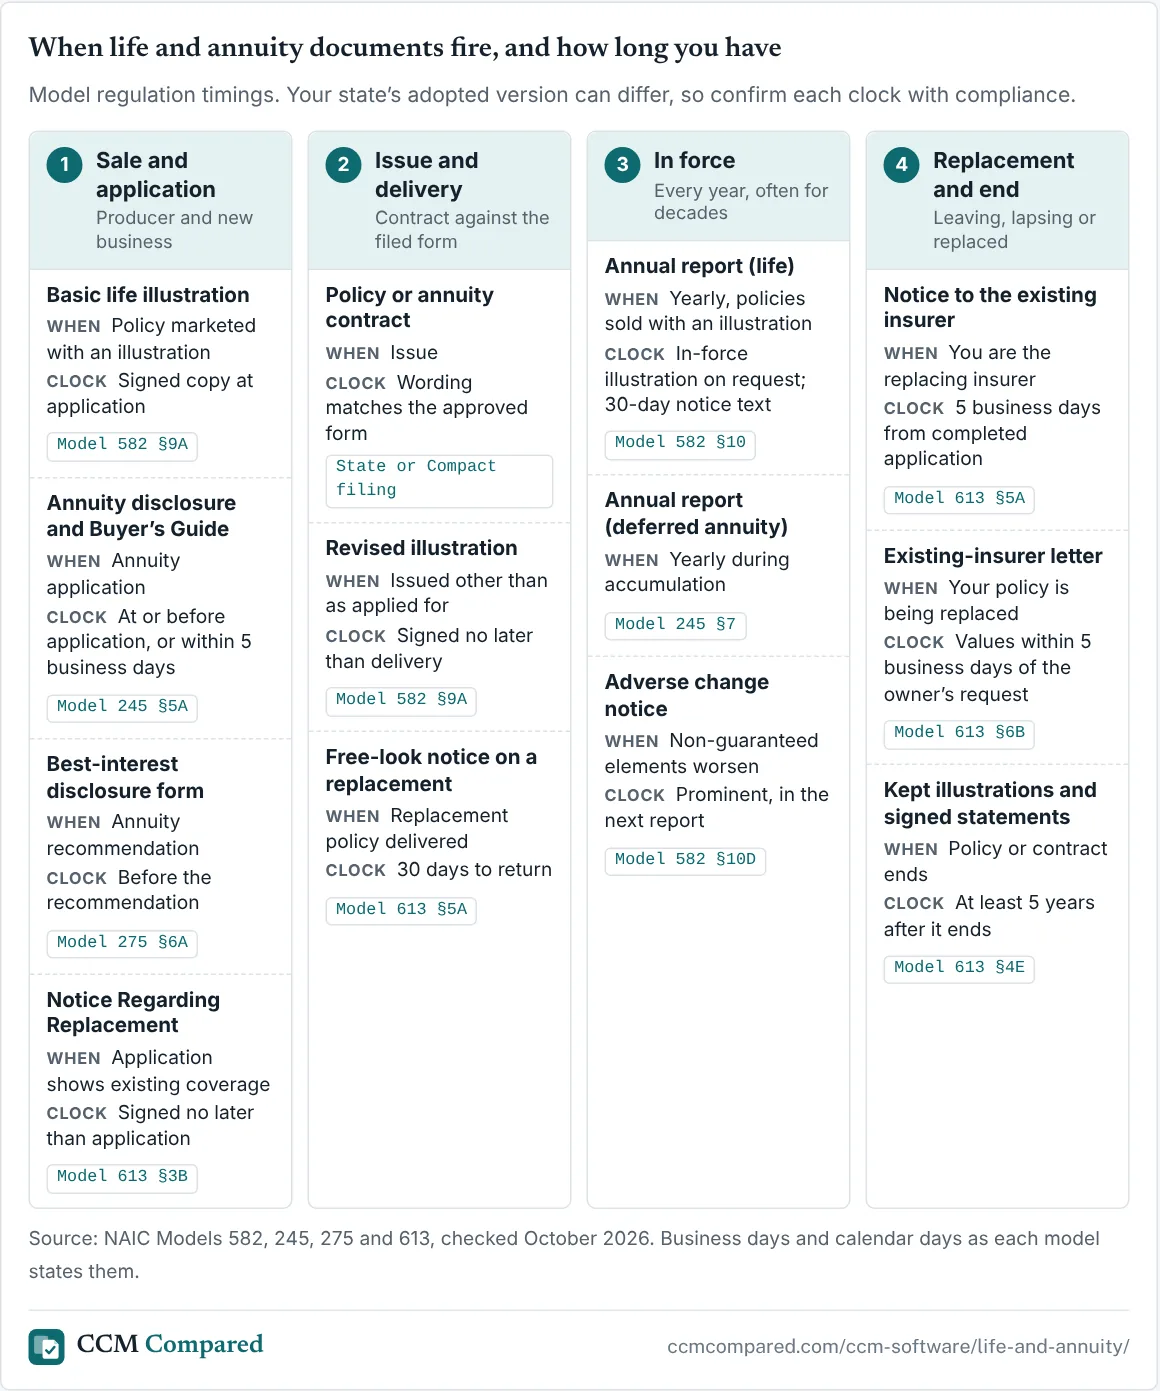
Most correspondence inventories list documents by name. This view lists them by when they fire and how long you have, which is how your production schedule actually runs.
Model regulation timings. Your state’s adopted version can differ, so confirm each clock with compliance.
-
Sale and application
Producer and new business
-
Basic life illustration
When Policy marketed with an illustration
Clock Signed copy at application
Model 582 §9A
-
Annuity disclosure and Buyer’s Guide
When Annuity application
Clock At or before application, or within 5 business days
Model 245 §5A
-
Best-interest disclosure form
When Annuity recommendation
Clock Before the recommendation
Model 275 §6A
-
Notice Regarding Replacement
When Application shows existing coverage
Clock Signed no later than application
Model 613 §3B
-
-
Issue and delivery
Contract against the filed form
-
Policy or annuity contract
When Issue
Clock Wording matches the approved form
State or Compact filing
-
Revised illustration
When Issued other than as applied for
Clock Signed no later than delivery
Model 582 §9A
-
Free-look notice on a replacement
When Replacement policy delivered
Clock 30 days to return
Model 613 §5A
-
-
In force
Every year, often for decades
-
Annual report (life)
When Yearly, policies sold with an illustration
Clock In-force illustration on request; 30-day notice text
Model 582 §10
-
Annual report (deferred annuity)
When Yearly during accumulation
Model 245 §7
-
Adverse change notice
When Non-guaranteed elements worsen
Clock Prominent, in the next report
Model 582 §10D
-
-
Replacement and end
Leaving, lapsing or replaced
-
Notice to the existing insurer
When You are the replacing insurer
Clock 5 business days from completed application
Model 613 §5A
-
Existing-insurer letter
When Your policy is being replaced
Clock Values within 5 business days of the owner’s request
Model 613 §6B
-
Kept illustrations and signed statements
When Policy or contract ends
Clock At least 5 years after it ends
Model 613 §4E
-
Source: NAIC Models 582, 245, 275 and 613, checked October 2026. Business days and calendar days as each model states them.
The last column matters most for platform choice. A letter for a policy sold in 1998 has to render from today’s platform, with today’s rules, on demand.
Forms are filed once and live for decades
Your contract wording is filed and approved before you sell, either state by state or through the Interstate Insurance Product Regulation Commission. The Compact reviews asset-protection products such as life insurance and annuities against uniform standards and has 48 member jurisdictions, with South Dakota joining in 2024.
State filings add their own detail. New York’s SERFF guidelines for life insurers, for example, want the form number exactly as it appears in the lower left corner of the form, and variable text shown in brackets. Your templates should carry the same form number and only vary where the filing shows brackets.
See which capabilities matter most to you
Tick the documents your blocks of business produce. The list underneath ranks capabilities by how many of your documents need them.
A dot means the document normally relies on that capability. Product and state add more, so check with compliance.
Scroll the table sideways to see every capability.
| Document and rule | Locked filed wording | Form number and bracketed variables | Policy admin data feed | Values passed in, never retyped | On-demand generation | Anniversary or year-end batch | Renders closed blocks and old forms | Archive of the sent copy |
|---|---|---|---|---|---|---|---|---|
| State or Compact filing | ● | ● | ● | ● | ● | |||
| Model 582 | ● | ● | ● | ● | ● | |||
| Model 245 | ● | ● | ● | ● | ||||
| Model 275 | ● | ● | ● | |||||
| Model 582 §10 | ● | ● | ● | ● | ● | ● | ||
| Model 245 §7 | ● | ● | ● | ● | ● | |||
| Model 613 | ● | ● | ● | ● | ● | ● | ||
| ● | ● | ● | ● |
Rules: NAIC Models 245, 275, 582 and 613 and New York DFS SERFF guidelines, checked October 2026. Capability mapping is our model of typical life and annuity production.
Two columns separate life from other insurance: values passed in from the admin system, and closed blocks that still need letters. Test both on your oldest products.
SmartCOMM alternatives for life and annuity carriers
These platforms have documented life or annuity work in trade press or labelled press releases. Ratings aren’t life-specific; every number is in our CCM benchmark.
Best for carriers on Sapiens L&A, and anyone consolidating correspondence
- 4.8 ★130 Gartner reviews
- July 2020Sapiens L&A integration announced
Sapiens announced in 2020 that Inspire would integrate with Sapiens CoreSuite for Life & Annuities. In 2018, Quadient announced that the group division of Ameritas, whose parent is Ameritas Life Insurance Corp., had cut a document process from 120 minutes to 15 with Inspire.
Best for large annual statement runs and multilingual correspondence
- 4.4 ★76 Gartner reviews
Equitable Life of Canada moved its statements, claims letters, cheques and contracts onto one platform in several languages when the product was HP Exstream, pulling member and policy data from XML and flat files. Reviewers praise its batch processing, which suits anniversary and year-end runs.
Watch out: the public life case is old, so ask for a current life or annuity reference.
Best for carriers already on Oracle, including OIPA
- 4.0 ★28 G2 reviews
- 90%annuity policy production automated at FBL, per Oracle
Trade press, drawing on an Oracle case study, reported that FBL Financial Group automated 90% of its annuity policy production with Documaker and produced PDF packages for electronic filing with state regulators. Oracle’s policy admin system for individual and group life and annuity is listed in Celent’s vendor directory.
Watch out: the annuity example dates from 2009, so ask what has changed and how it connects to your OIPA release.
Experlogix (formerly Xpertdoc)
Best for small and mid-sized life carriers on Microsoft tools
- 4.7 ★11 G2 reviews
Trade press reported Xpertdoc’s 2014 partnership with Adminovate, which builds core systems for life, health and annuity carriers, and Kansas City Life’s 2017 deployment of the platform for customer communications.
Watch out: G2 files it under document generation, so test it on your full annual statement volume.
Strong CCM leaders without public life proof
These platforms have strong insurance-wide evidence but little public life or annuity detail. Worth a look if their strengths match your problem; just ask for life references.
| Platform | Gartner rating | Why it might fit | Ask the vendor |
|---|---|---|---|
| Messagepoint | 4.4 from 69 reviews | Named a Luminary in Celent’s 2024 insurance CCM report, as Messagepoint announced. Suits carriers with thousands of overlapping letters | Two life or annuity references |
| Precisely EngageOne | 4.1 from 12 reviews | Its September 2026 release names insurance as a target industry | Which life or annuity carriers run it today |
| ISIS Papyrus | 4.5 from 92 reviews | Combines communications with case management, which suits policy service teams | A life or pensions reference on your volumes |
Gartner Peer Insights ratings, October 2026. Large template estate to clean up first? See template rationalization.
Running SmartCOMM today? Start with renewal and exit terms
Smart Communications sells CCM to insurers, and trade press coverage of its insurance work discusses life and annuity customers. If you’re on SmartCOMM, your contract dates decide how much room you have.
- Find the notice date in your order form and work back about a year. Our SmartCOMM contract renewal plan has the timeline.
- Get archive export terms in writing. Under the replacement model, kept illustrations and signed statements must last at least five years after a policy ends, so your sent-copy archive outlives any contract. Ask for a full export with policy number, form number and date.
- Get template export terms, with each template’s form number and version history, so you can show which filed version produced which document.
- Ask for a short extension sized to a migration, with per-unit prices and an increase cap, instead of a long renewal.
- Price a competitor on the same volumes. Start with SmartCOMM alternatives, then plan the move with our guide to migrating off SmartCOMM.
What to put in your RFP
These lines follow from the rules above. Copy them from our CCM RFP template.
- A named connector to your policy admin system, with the supported release and a carrier you can call.
- Form numbers and bracketed variables that match your filings, with locked wording everywhere else.
- Values passed in from the admin system for illustrations and annual reports, never recalculated or retyped.
- Anniversary and year-end batches plus on-demand letters from the same templates.
- Closed-block support: render a letter for your oldest in-force product on request.
- A replacement letter and in-force values turnaround comfortably inside five business days.
- An archive of what was sent, searchable by policy number, form number and date, kept for the life of the policy plus your retention period.
- Full archive and template export, priced in the contract.
How to test the shortlist
Use your own data and your oldest products, because that’s where platforms fail.
- Render an annual report for a 20-year-old universal life policy with an adverse change notice.
- Generate an existing-insurer replacement letter on demand and time it.
- Change one bracketed variable in a filed contract and show the approval trail and the form number on output.
- Run a year-end batch at peak volume.
- Score each vendor with our CCM vendor scorecard.
Also selling retirement and investment products through broker-dealers? See wealth management client communications software.
Handling P&C claims too? See claims correspondence software.
Get a vendor shortlist for your requirements
Tell us what you run today and what you need. We reply with the two or three platforms that fit, and why.
Email hello@ccmcompared.comWe only share your details with a vendor if you ask us to.
Frequently asked questions
Is illustration software the same as life insurance document generation software?
No. Illustration and annuity sales tools run at the point of sale and calculate projected values. A CCM platform composes the contract, annual statements, notices and letters for the life of the policy, with filed wording locked and a copy of what was sent.
How often must a life insurer send an annual report?
Under the NAIC Life Insurance Illustrations Model Regulation, at least once a year for policies sold with an illustration, showing values, death benefit, loans and any adverse change in non-guaranteed elements. The NAIC Annuity Disclosure Model sets a similar yearly report for deferred annuities. Your state’s adopted version governs.
How fast must a carrier respond when a policy is being replaced?
Under NAIC Model 613, the replacing insurer notifies the existing insurer within five business days of a completed application. The existing insurer then sends the owner a letter offering current policy values, including an in-force illustration or policy summary, and provides them within five business days of the owner's request.
Do life and annuity forms have to be filed in every state?
Not always. The Interstate Insurance Product Regulation Commission reviews asset-protection products, such as life insurance and annuities, against uniform standards for its 48 member jurisdictions. Products outside the Compact are filed state by state, usually through SERFF.
Does Smart Communications sell to life and annuity carriers?
Smart Communications sells CCM to insurers, and trade press coverage of its insurance work discusses life and annuity customers. If you’re on SmartCOMM, compare alternatives with life evidence before your renewal notice date.
Charts from this guide
Free to share with a link back to this page. Tap a chart for the full-size image.
Sources
- NAIC: Life Insurance Illustrations Model Regulation (Model 582)
- NAIC: Life insurance illustrations topic page
- NAIC: Annuity Disclosure Model Regulation (Model 245)
- NAIC: Suitability in Annuity Transactions Model Regulation (Model 275)
- NAIC: Government affairs brief on the annuity suitability best interest model
- NAIC: Life Insurance and Annuities Replacement Model Regulation (Model 613)
- Insurance Compact: South Dakota joins as its 48th member jurisdiction (February 2024)
- North Dakota Insurance Department: North Dakota enacts legislation to join the Insurance Compact (April 2023)
- New York DFS: General SERFF guidelines for form filings, life insurers
- Mass.gov: General filing instructions for life and annuity
- PR Newswire (press release): Sapiens partners with Quadient to enhance digital engagement and experience across products, July 2020
- SalesTechStar: Quadient brings new and expanded capabilities to the Ameritas group division (December 2018)
- InsuranceTech: Equitable Life of Canada uses HP Exstream for customer communications
- Insurance-Canada.ca: FBL Financial Group cuts policy production time by 80% (April 2009)
- Celent directory: Oracle Insurance Policy Administration for Life and Annuity
- Dig-In: Xpertdoc partners with Adminovate (March 2014)
- Dig-In: KC Life deploys new document management system (May 2017)
- G2: Experlogix Document Automation (formerly Xpertdoc) reviews
- FinTech Global: How Smart Communications helps insurers engage in smarter customer conversations (December 2022)
- Business Wire (press release): Messagepoint a Luminary in Celent's 2024 insurance CCM report
- Celent: CCM Solutions, Global Insurance Edition 2024
- PR Newswire (press release): Precisely expands AI capabilities in EngageOne RapidCX, September 2026
- TrustRadius: OpenText Exstream reviews
- Gartner Peer Insights: Customer Communications Management Software market
- G2: Oracle Documaker reviews
CCM Compared is independent and not affiliated with Smart Communications or any vendor named here. Product names are trademarks of their owners and are used to identify products only. See our methodology and disclosure. Spotted an error? Request a correction.