Loan document generation software: what your LOS covers, and where CCM fits
For mortgage disclosures and closing packages, your loan origination system plus its document provider is usually the right loan document generation software. Add a CCM platform when servicing, default and cross-product letters outgrow it: Messagepoint for mortgage servicers, MHC for auto and equipment finance on Odessa, and Newgen if you want origination and communications from one vendor.
Looking for loan document generation software? First work out which documents you mean. The Loan Estimate, Closing Disclosure and closing package usually come from your loan origination system (LOS) and its document provider. The letters that follow, for years, are a different job.
That second job is where a customer communications management (CCM) platform earns its keep: servicing notices, default letters, and letters across mortgage, auto, card and business loans. This guide shows where the line sits, which platforms have public lending proof, and what to test. It isn’t legal advice. For the full vendor list, see our CCM software guide.
Pick by your situation
Short on time? Start here.
- Mortgage servicer rewriting borrower letters all the time? Look at Messagepoint.
- Auto or equipment finance on Odessa? Look at MHC.
- Want origination and communications from one vendor? Look at Newgen.
- On nCino and only need loan agreements and letters? Look at Conga Composer.
- Only need TRID disclosures and closing packages? Your LOS may be enough.
- Running SmartCOMM? Jump to renewal and exit terms.
When your LOS is enough
Most mortgage lenders don’t build their Loan Estimate or Closing Disclosure in a CCM tool. The LOS holds the data and tracks the dates, and a document provider plugged into it produces the package.
Take ICE’s Encompass. In 2021 ICE announced Encompass eClose to run closings inside the LOS, from ordering documents to investor delivery, with ink, hybrid and full eClosings. Document providers plug in too: First American Docutech announced an Encompass integration in 2020 that updates disclosure tracking fields and delivers documents into Encompass.
| You need | Usually enough | Add a CCM platform when |
|---|---|---|
| Loan Estimate and Closing Disclosure | LOS plus its document provider | Rarely. Keep TRID where the dates are tracked. |
| Closing package and e-closing | LOS e-close tools or document provider | Rarely. |
| Approval, conditions and decline letters | LOS templates for one product line | You run several LOSs or product lines and want one approved wording library. |
| Servicing and default notices | Servicing system letters at small scale | Volume, frequent rule changes or many states make IT-led template edits too slow. |
| Statements, payoff and year-end letters | Servicing system | You want print, email and portal from one template, with an archive of the sent copy. |
Not sure which side of the line you’re on? Our CCM vs document generation guide explains the difference.
The rules your lending documents run on
Lending documents fail on dates more than wording. Your platform has to know when each one is due, and prove when it went out.
TRID: the Loan Estimate and Closing Disclosure clock
Regulation Z sets two clocks: one starts at application, the other counts back from consummation.
| Document | Deadline | Rule |
|---|---|---|
| Loan Estimate | By the 3rd business day after the application, and by the 7th business day before consummation | 12 CFR 1026.19(e)(1)(iii) |
| Revised Loan Estimate | Never on or after the day you provide the Closing Disclosure | 1026.19(e)(4)(ii) |
| Closing Disclosure | Received at least 3 business days before consummation | 1026.19(f)(1)(ii) |
| Corrected Closing Disclosure | New 3-day wait if the APR becomes inaccurate, the loan product changes or a prepayment penalty is added | 1026.19(f)(2)(ii) |
| Notice of right to an appraisal copy | By the 3rd business day after the application (first-lien dwelling loans) | Regulation B, 1002.14(a)(2) |
Mail a Loan Estimate or Closing Disclosure instead of handing it over, and the borrower is treated as receiving it three business days later. So your system needs the send date, the channel and the rule’s clock in one place.
Adverse action notices
Decline and counteroffer notices follow Regulation B. We cover reason codes and timing in our CCM software for banks guide, so we won’t repeat it here.
Regulation X: the delinquency clock for servicers
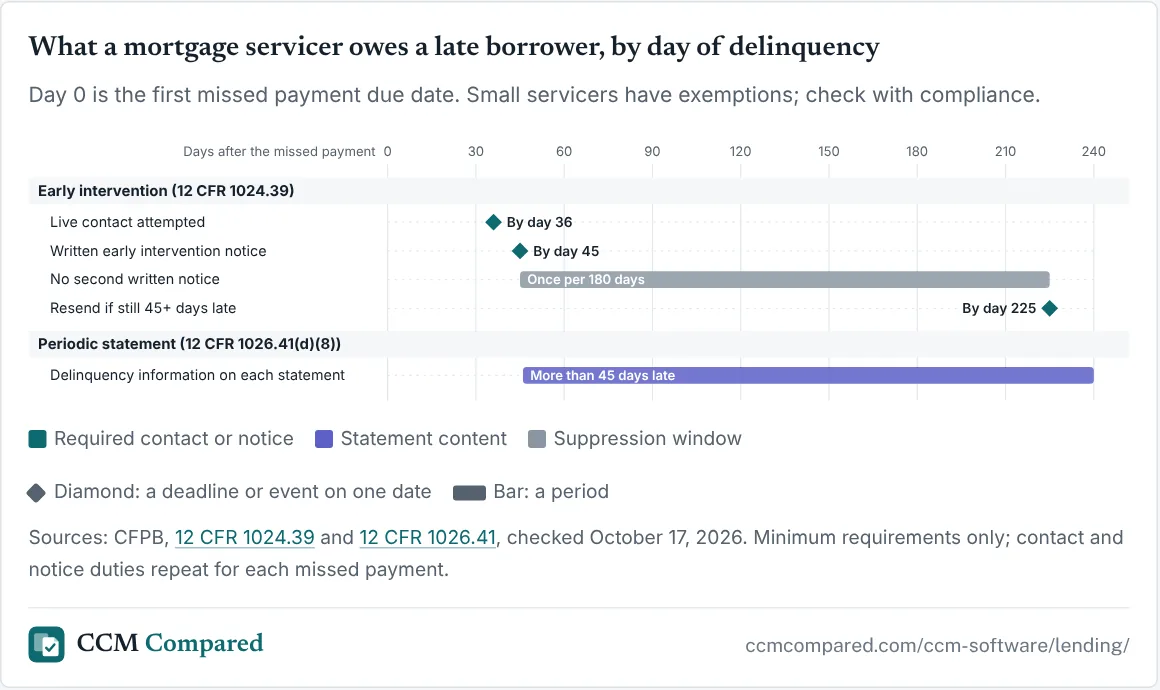
Once a loan is in servicing, the deadlines count from missed payments. A CCM platform has to send some notices on time and hold others back.
Day 0 is the first missed payment due date. Small servicers have exemptions; check with compliance.
Sources: CFPB, 12 CFR 1024.39 and 12 CFR 1026.41, checked October 17, 2026. Minimum requirements only; contact and notice duties repeat for each missed payment.
The notice is also a content job. It has to invite contact, give a phone number and mailing address, describe loss mitigation options where they apply, and point to housing counselors.
Loss mitigation adds its own letters. When an application arrives well before any foreclosure sale, a servicer acknowledges it within 5 business days and decides a complete one within 30 days, with specific reasons for any loan modification denial (12 CFR 1024.41).
See which capabilities matter most to you
Tick the documents you produce. The list underneath ranks capabilities by how many of your documents need them, so you know what to prove first.
A dot means the document relies on that capability. State rules, investor guides and product terms add more.
Scroll the table sideways to see every capability.
| Document and rule | Live data from the LOS or servicing system | Deadline tracking and proof of send date | Locked regulatory wording | Reasons passed in as data | Frequency and suppression rules | Business-user edits with approval | E-signature and e-delivery | Cycle batch at volume | Archive of the sent copy |
|---|---|---|---|---|---|---|---|---|---|
| Regulation Z, 12 CFR 1026.19(e) and (f) | ● | ● | ● | ● | ● | ||||
| ● | ● | ● | ● | ||||||
| Regulation B, 12 CFR 1002.14 | ● | ● | ● | ● | |||||
| Regulation Z, 12 CFR 1026.41 | ● | ● | ● | ● | |||||
| Regulation X, 12 CFR 1024.39 | ● | ● | ● | ● | ● | ● | |||
| Regulation X, 12 CFR 1024.41 | ● | ● | ● | ● | ● | ||||
| ● | ● | ● | ● | ● |
Rules: CFPB Regulations B, X and Z, checked October 17, 2026. Capability mapping is our model of typical lender production.
If your ticks land mostly on the first three rows, stay with your LOS tools. If they land on the bottom four, you’re shopping for CCM.
SmartCOMM alternatives for lenders: who has lending proof
Plenty of CCM vendors market to lenders. Fewer have a lending customer, LOS partner or mortgage award on record outside their own website. Read across a row to see what’s public and how old it is.
Dates are when it was announced or reported. SmartCOMM shown for reference. As of October 17, 2026.
| Vendor | Origination or LOS link | Servicing and default | Business users edit disclosures | Source type |
|---|---|---|---|---|
| Messagepoint | No public record found | MortgagePoint Tech Excellence Award, second year running; HousingWire Tech100 in 2025 1 | No-code editing of borrower communications 2 | Trade press and press releases |
| MHC NorthStar | Embedded in Odessa lending workflows for auto and equipment finance 3 | Embedded in Odessa servicing workflows 3 | Business teams update disclosures and notices, per the announcement 3 | Trade press |
| Newgen | Its own LOS chosen by United Community for small business lending 4 | No public record found | No public record found | Trade press and press release |
| Quadient Inspire | Mobile tool pitched for mortgage applications 6 | No public record found | No public record found | Press release |
| OpenText Exstream, Precisely | Ask for named lending references and LOS connectors | Ask | No public record found | Vendor pages only |
| SmartCOMMreference | CGI Credit Studio partnership names loan origination and onboarding 7 | Same release names servicing and default management 7 | No public record found | Press release |
None of the announcements above names an Encompass or nCino connector. So make the LOS connector a demo item, not a checkbox.
The best platforms for lending communications
These picks pair each platform’s lending record with its review and analyst record. Ratings aren’t lending-specific; every number is in our CCM benchmark.
Best for mortgage servicers whose borrower letters change with every rule or investor update
- 4.4 ★69 Gartner ratings
- LeaderIDC MarketScape 2026
- 2025HousingWire Tech100
Messagepoint pitches itself to servicers as a no-code way to bring borrower letters in-house, away from IT and print vendors. In 2026 it announced a MortgagePoint Tech Excellence Award for the second year running. In 2023 it announced mortgage servicing consultancy Newbold Advisors as a referral partner.
Watch out: its mortgage releases name no servicing system integrations, so ask for a live demo on yours.
MHC NorthStar
Best for auto and equipment finance lenders running Odessa
- LeaderQKS SPARK Matrix 2026
- Jun 2026Odessa partnership
MHC and Odessa announced in June 2026 that Odessa clients can embed NorthStar CCM in their lending and servicing workflows. The pitch: business teams update disclosures and notices when rules or products change, without custom code.
Watch out: there’s no review base in our benchmark yet, so ask for two Odessa lenders to call.
Newgen
Best for banks that want loan origination and communications from one vendor
- EvaluatedQKS SPARK Matrix 2026
- 2023U.S. bank LOS deal
United Community announced in 2023 that it picked Newgen’s loan origination solution for small business construction, term, line of credit and commercial real estate loans. Separately, Bermuda’s Clarien Bank planned to use Newgen’s CCM suite for loan, card and savings templates, according to Retail Banker International.
Watch out: the United Community announcement covered origination only, so confirm that CCM is in scope and priced.
Conga Composer
Best for nCino banks that need loan agreements and letters, not regulated batch notices
- 4.4 ★918 G2 reviews
nCino says in its annual report that fundamental parts of its platform are built on Salesforce. That makes Salesforce document tools a natural fit for commercial loan agreements and approval letters. Ask for a demo built on your own nCino objects.
Watch out: it’s a Salesforce document tool, not a CCM platform. It won’t run servicing batches.
Lending inside a bank that’s standardizing on one CCM platform? Quadient Inspire and OpenText Exstream lead our picks for banks, and either can carry lending letters too. Ask each for lending references.
Running SmartCOMM for lending today?
Smart Communications says SmartCOMM is used by hundreds of financial institutions, and in 2023 announced a CGI Credit Studio partnership in a release naming loan origination, servicing and default use cases. In 2025 it announced a majority investment from Cinven. Your renewal is the moment to set your exit terms.
- Find your notice date in the order form. Plan back from it, not the renewal date. Our SmartCOMM contract renewal plan has the dated steps.
- Get export rights in writing: templates, rules, shared content and the archive of sent notices, with retention dates intact.
- Inventory every lending connector, including CGI or LOS links, and who maintains each one.
- Ask for transition access after notice, so you can run old and new side by side through a full delinquency cycle.
- Price a short extension sized to a migration, not a multi-year term.
Then compare your options in SmartCOMM alternatives and plan the move with our guide to migrating off SmartCOMM.
What to put in your RFP
These lines come from the rules above. Add them to our CCM RFP template.
- Named connectors to your LOS and servicing system, with a live demo on your release.
- Send-date proof for every notice with a deadline, by channel.
- Frequency rules that suppress repeat notices, such as one early intervention notice per 180 days.
- Reasons as data for loss mitigation denials, never typed.
- Business-user edits with approval and an audit trail.
- E-delivery and e-signature for approval letters and servicing notices.
- An archive of each document as sent, searchable by loan number and date.
- Two lender references of your type you can call without the vendor on the line.
Score the answers with our CCM vendor scorecard.
Managing client assets too? See CCM software for wealth management.
Get a vendor shortlist for your requirements
Tell us what you run today and what you need. We reply with the two or three platforms that fit, and why.
Email hello@ccmcompared.comWe only share your details with a vendor if you ask us to.
Frequently asked questions
What is loan document generation software?
Software that builds loan documents from application and loan data: disclosures, approval letters, closing packages and later servicing notices. Mortgage lenders usually get the disclosures and closing package from their LOS and a document provider, and use a CCM platform for the letters that follow.
How fast must a lender send the Loan Estimate?
No later than the third business day after receiving the application, and no later than the seventh business day before consummation (12 CFR 1026.19(e)(1)(iii)). If you mail it, the borrower is treated as receiving it three business days after you mail it.
When does a corrected Closing Disclosure restart the three-day wait?
When the APR becomes inaccurate, the loan product changes, or a prepayment penalty is added (12 CFR 1026.19(f)(2)(ii)). Other changes still need a corrected disclosure at or before closing, without a new waiting period.
When must a mortgage servicer send the early intervention notice?
No later than the 45th day of delinquency, and generally no more than once in any 180-day period (12 CFR 1024.39(b)(1)). Live contact has to be attempted by day 36.
Can nCino generate loan documents with a Salesforce document tool?
Often, yes, because fundamental parts of nCino are built on Salesforce, according to nCino’s annual report. Ask any Salesforce document generation vendor to demo against your own nCino objects before you count on it.
Charts from this guide
Free to share with a link back to this page. Tap a chart for the full-size image.
Sources
- CFPB: 12 CFR 1026.19 (Regulation Z, Loan Estimate and Closing Disclosure timing)
- eCFR via Cornell LII: 12 CFR 1026.19
- CFPB: 12 CFR 1026.41 (Regulation Z, mortgage periodic statements)
- CFPB: 12 CFR 1024.39 (Regulation X, early intervention)
- CFPB: 12 CFR 1024.41 (Regulation X, loss mitigation)
- CFPB: 12 CFR 1002.14 (Regulation B, appraisals and valuations)
- SEC: nCino, Inc. Form 10-K for fiscal 2026
- Mondo Visione: ICE Mortgage Technology launches Encompass eClose, April 2021
- Business Wire (press release): First American Docutech integration with Encompass, November 2020
- Business Wire (press release): Docutech expands document solutions across the loan lifecycle, October 2025
- HousingWire: 2025 Tech100 winner Messagepoint
- Business Wire (press release): Messagepoint MortgagePoint Tech Excellence Award, June 2026
- CUInsight (press release): Messagepoint partnership with Newbold Advisors, July 2023
- Gartner Peer Insights: Messagepoint
- BNN Bloomberg (press release): Messagepoint a Leader in the 2026 IDC MarketScape
- DOCUMENT Strategy Media: MHC and Odessa partner for asset finance lenders, June 2026
- QKS Group: MHC in the SPARK Matrix for CCM 2026
- iTWire (press release): United Community partners with Newgen for loan origination, November 2023
- Retail Banker International: Clarien Bank taps Newgen Software for customer communications
- QKS Group: SPARK Matrix for Customer Communications Management, Q3 2026
- G2: Conga Composer vs Experlogix Document Automation
- CUInsight (press release): Quadient at FinovateSpring 2018
- GlobeNewswire via FinancialContent (press release): Smart Communications and CGI partnership, April 2023
- Business Wire (press release): Smart Communications announces investment from Cinven, August 2025
CCM Compared is independent and not affiliated with Smart Communications or any vendor named here. Product names are trademarks of their owners and are used to identify products only. See our methodology and disclosure. Spotted an error? Request a correction.